Your Debt Dashboard
The answers you want first, on one screen.
- Your total debt and estimated debt-free month
- The debt to focus on next
- A progress bar for every debt
- Up to three “needs attention” flags, so nothing sneaks up on you
For people who pay every month and still can’t see the end
Put every debt in one private place. See which one to pay first, and what an extra $100 a month really changes.
No bank login · No account · No subscription · Works offline
From a founder who paid off about $20,000 of debt in roughly three years.
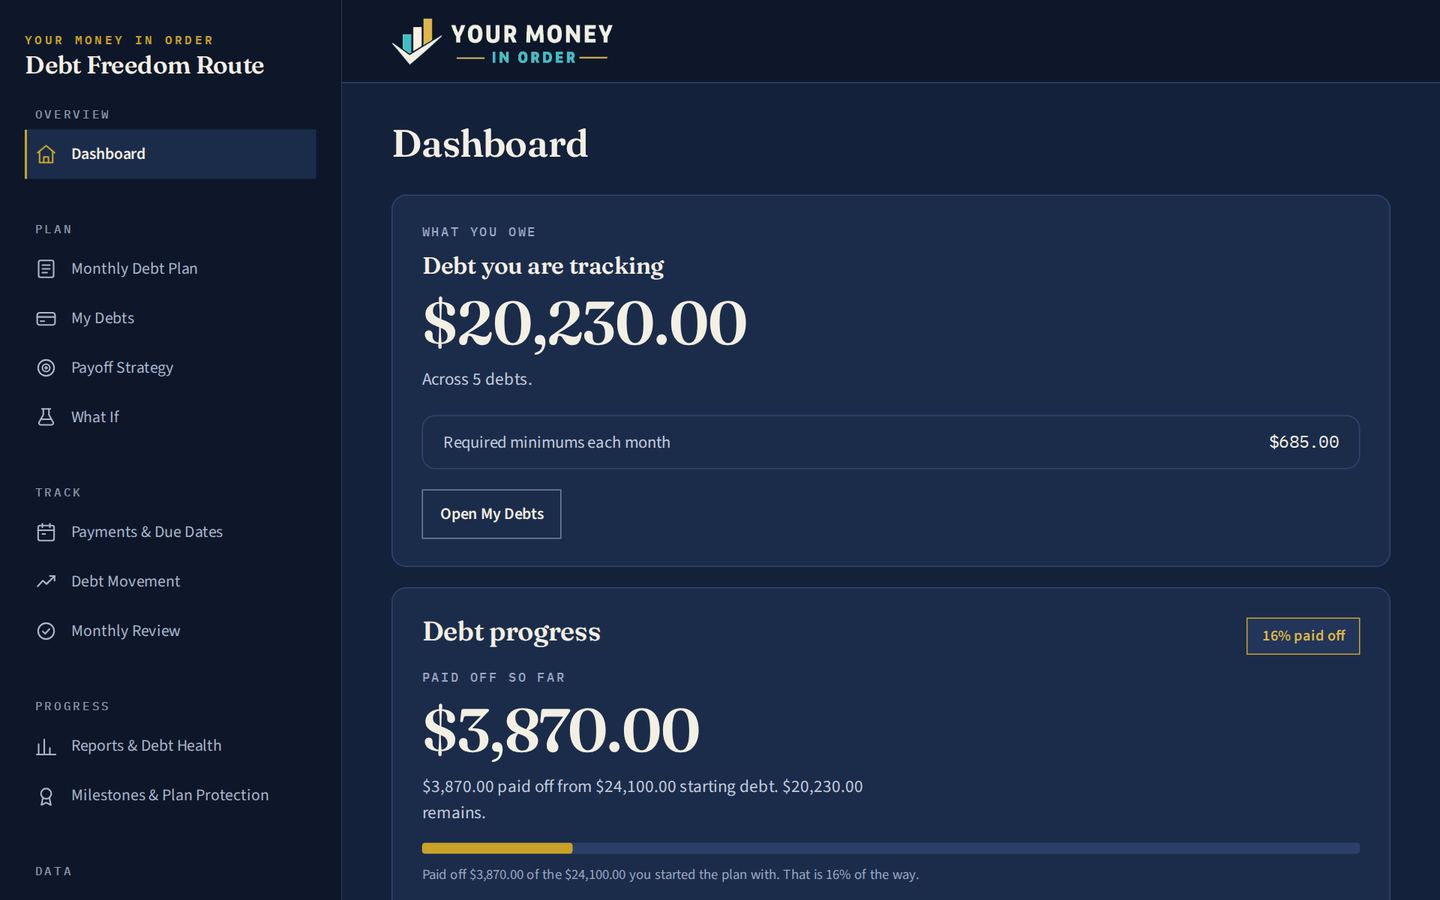
The real Debt Freedom Route dashboard, filled with example numbers.
You’re not ignoring your debt. You pay it, on time, every month.
But the balances barely move. And one question keeps coming back, usually late at night:
When does this actually end?
Minimum payments keep your accounts current. They don’t give you a route out.
Say you owe $6,000 on a card at 24% APR. Here’s one ordinary month:
You paid $180. The balance went up $40.
Nothing is wrong with you. It’s math nobody showed you. Debt Freedom Route shows it to you, month by month.
Why I made this
For about 17 years I worked in IT and earned well above average. I still lived paycheck to paycheck.
By my mid-30s I had three maxed-out credit cards and about $20,000 of debt.
I took out a personal loan to clear one card. The card filled back up. Now I had both.
Then I lost my job. I found another in about five weeks. With debt and no savings, those weeks were frightening.
So I did what I’d been avoiding. I took a financial-literacy course and looked at the whole picture.
Then I built a debt freedom plan covering all three cards and the loan.
Here’s what surprised me. The weight lifted before the debt was gone.
For the first time, I could see a route instead of a pile of balances.
I paid off about $20,000 over roughly three years. Not overnight. One month at a time, on a plan I could see.
Debt Freedom Route is built around what helped me. One private place. A clear order. An end date.
And an honest check that the debt is really going down.
Your numbers and your timeline will be your own. But you deserve to see your route too.
Balances, rates, minimums and due dates. Cards, loans, BNPL, medical bills and more.
The Monthly Debt Plan works out what your month can really spare, after essentials, irregular costs and a small buffer.
Minimums only, Snowball, Avalanche or your own order, side by side. Pick the one that fits you.
Log payments and statements. See whether your debt is really going down, and what’s next.
Instant download · One-time payment · Your numbers stay on your computer
One private tool that plans your payoff, tracks it, and tells you the truth about your progress.
The answers you want first, on one screen.
Know what you can safely put toward debt.
See your options side by side.
Test ideas without touching your plan.
Stay on top of every payment.
The honest check most tools skip.
See how far you’ve come.
Progress you can feel before zero.
Your numbers never leave your computer.
Works with credit cards, BNPL, personal loans, auto loans/car finance, medical bills, student loans, mortgages and more.
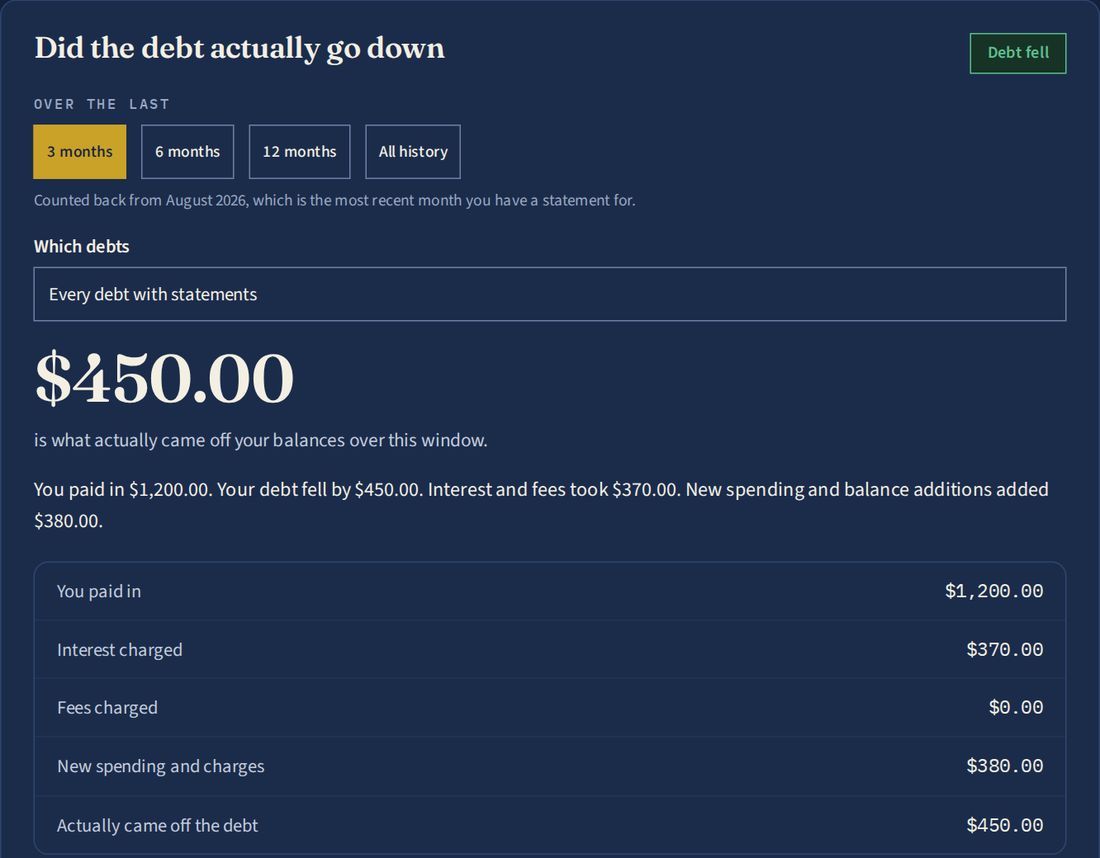
Debt Movement, on screen
Debt Movement adds up your statements and shows where the money went: interest, fees, and new spending that quietly replaced your progress.
Real screen, example numbers.
A $6,000 card at 24% APR costs about $120 in interest in a single month.
Debt Freedom Route costs $37. Once.
No subscription. Nothing extra to unlock. You get one file straight after checkout, and it’s yours to keep.
See it work
Two debts: $2,500 at 8% APR and $6,000 at 24% APR. Minimums of $80 and $180. Then $200 a month extra.
| Route | Debt-free in | Interest paid |
|---|---|---|
| Minimums only | 56 months | $4,299 |
| Snowball + $200 | 23 months | $1,962 |
| Avalanche + $200 | 22 months | $1,541 |
Same debts. Add $200 a month, pick a route: about 34 months sooner and $2,759 less interest.
And just choosing the order changed the interest by $422. Debt Freedom Route shows you this for your own debts.
Example numbers for illustration. Your results depend on your own debts, rates and payments.
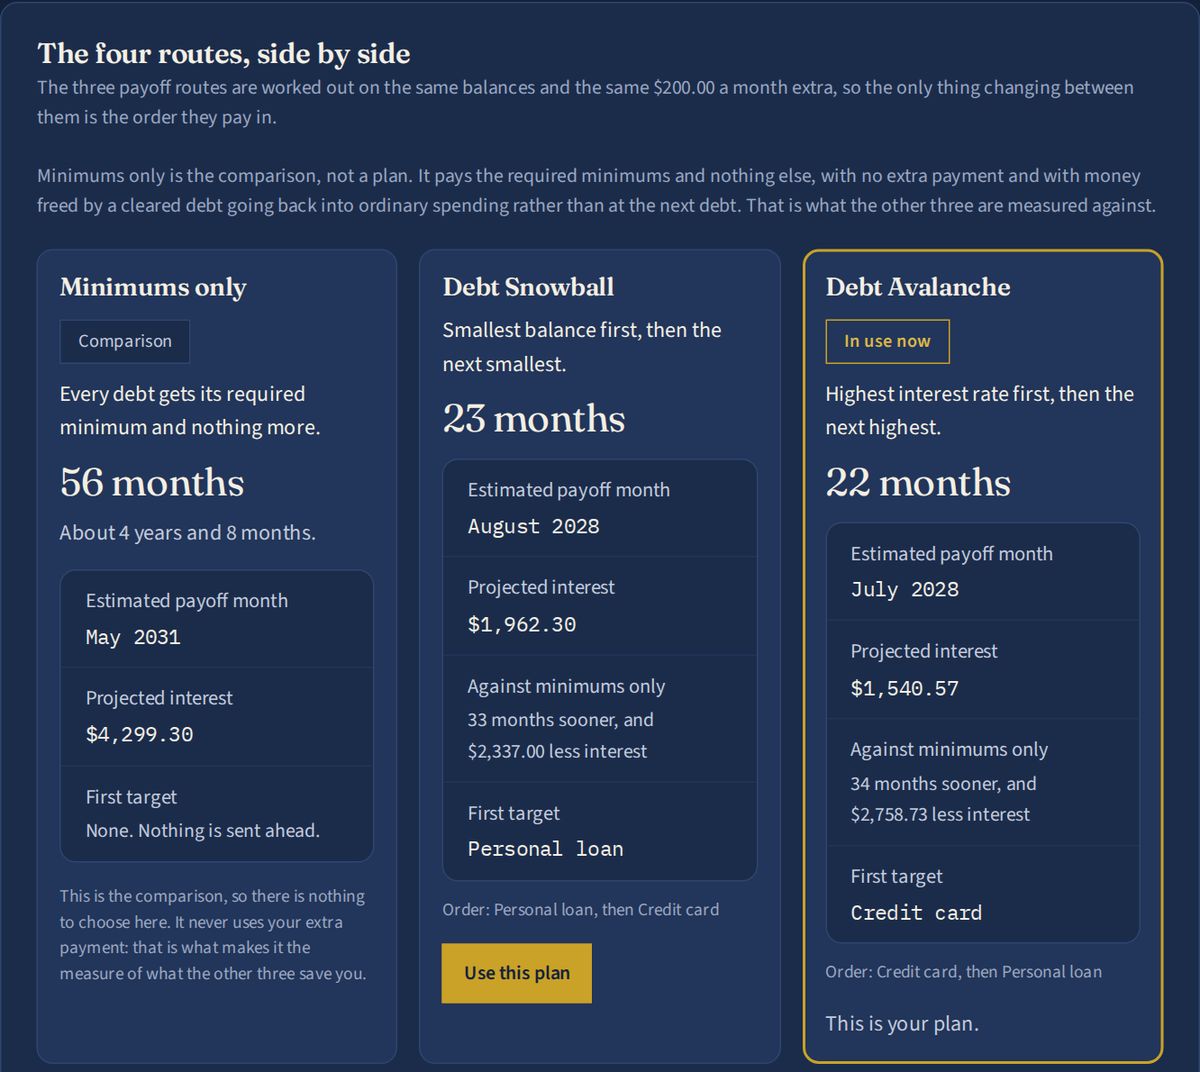
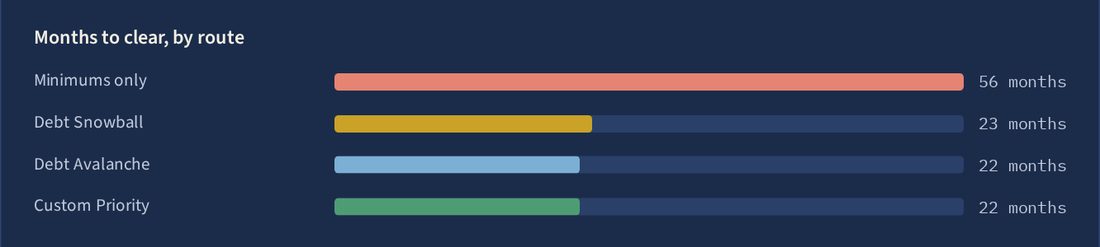
This exact example, loaded into the real Payoff Strategy screen.
Private, and tested
Before release, the whole tool was run on a computer with Wi-Fi off. It made zero network requests.
That means your debt numbers have nowhere to go. They stay on your computer.
Every payoff figure is checked against a reference calculator, with more than 3,000 automated checks run before release.
The top 5
You can, and it will give you a date. Debt Freedom Route does that too, then keeps going.
It also works out what you can safely afford, and compares four routes on your real numbers.
Then it tracks your payments and checks that your debt is really going down.
A calculator gives you a number. This gives you a route you can follow.
No. There’s no account, no login and no bank connection. You type in your own numbers.
Everything stays on your computer, and it works offline.
Most of us quit because the tool turns into a second job. Here, there are no formulas to build or fix. It does the math.
It’s made for a short monthly check-in: log payments, update balances, see what moved. Milestones and simple check-ins help you keep going.
That’s fine. Your minimums-only route is still worth seeing, because it shows you where you really stand.
The Monthly Debt Plan helps you find a safe extra amount, even $50, without leaving you short before payday. What-If shows what it changes.
Debt Freedom Route is built and tested for a desktop or laptop computer, in Chrome, Edge or Firefox.
You can buy it on your phone right now. Your download link comes by email, ready for when you’re at your computer.
Will it work for me?
Credit cards, store cards, BNPL, personal loans, auto loans/car finance, overdrafts and lines of credit.
Also medical bills, family loans, student loans, mortgages, and anything else with a balance.
No, it’s your choice. Put them in your payoff plan, or mark them “track only.”
Track-only debts stay visible and their minimums still count. The plan just doesn’t target them.
You don’t need to know yet. Snowball clears the smallest balance first, for quick wins.
Avalanche goes after the highest rate first, which usually saves more interest.
You’ll see both side by side, using your numbers, and choose with the facts in front of you. You can also set your own order.
Yes. You can add partner or spouse income and any joint debts, and plan together from the same file.
Update your Monthly Debt Plan to see what your month can support now, then adjust your extra payment.
Got a raise, a bonus or a tax refund? Try it in What-If first and see what it changes before you commit.
It happens, and there’s no judgment here. Debt Movement shows how new spending affected your balance, so you can see it, adjust and keep going.
You’re far from alone, and nobody sees this but you. No account, no bank login, no one to explain it to.
You start with the numbers, not judgment.
Yes. Choose USD, GBP, EUR, CAD or AUD. It shows your currency symbol. It doesn’t convert between currencies.
No. Debt Freedom Route works on its own. If you’ve already done the Money Reality Check, you can import your numbers in one step.
Have your latest statements handy: balances, interest rates, minimums and due dates. Most of setup is typing those in.
After that, a short check-in once a month keeps everything current.
Not right now, and I’d rather tell you that before you buy. This tool is for people who can keep up with their required payments.
If you’re struggling to keep up, please talk to a free, nonprofit credit counselor first.
In the US, the NFCC (nfcc.org) can connect you with one. In the UK, MoneyHelper (moneyhelper.org.uk) offers free, impartial help.
As soon as your debts are in, you’ll see your estimated debt-free month and the debt to focus on next.
The balances move as fast as your payments do. Debt Movement shows you, month by month, whether they really are.
Privacy and tech
On your computer, inside your browser, for that file only. Nothing is sent anywhere.
One thing to know: anyone who can use your computer, or open your backup file, may be able to see your numbers.
The backup file isn’t encrypted or password protected, so keep it somewhere safe.
No and no. It’s an interactive tool that opens in your web browser.
It works like a web page, but it lives on your computer. Nothing to install.
No. Once it’s downloaded, it works fully offline.
Yes. Open it in Chrome or Firefox. Both are free to download.
Save a backup file from Data and Settings, and keep it somewhere safe. After each check-in, save a fresh one.
On a new computer, or after clearing your browser, open the tool and restore from that file.
Buying
Straight after checkout you get your download. It’s one file. Save it to your computer, double-click, and it opens in your browser.
No. You pay $37 once. No monthly fee, and nothing extra to unlock.
No tool can promise that. It’s an estimate based on the numbers you enter.
Keep them up to date and your estimate stays close to real life.
No. It’s a planning and tracking tool. It doesn’t move money, contact lenders, reduce what you owe or check your credit report.
You stay in control of every payment.
No. I’m not a financial advisor. Debt Freedom Route helps you see your numbers and compare options, so you can make your own decisions.
Because it’s a digital file you keep as soon as you download it, all sales are final, except where the law says otherwise.
If the file won’t open or something isn’t working, just reply to your receipt email and I’ll help you sort it out.
Picture payday. You log your payments, see your debt-free month hold steady or move closer, and get on with your evening.
With Debt Freedom Route, you’ll have:
Instant download · No bank login · No subscription · Works offline
Best on a desktop or laptop. Buy on your phone now, and open it on your computer later.
P.S. The first thing my plan gave me wasn’t a zero balance. It gave me a route. I’d love for you to have yours.
Sab, Your Money In Order
Debt Freedom Route is a planning and tracking tool. It doesn’t make payments, contact lenders or reduce your debt.
It doesn’t check your credit report or give personal financial advice.
Payoff dates and interest figures are estimates based on the numbers you enter.
If you can’t currently cover essentials or your minimum payments, please speak to a nonprofit credit counselor first.
All sales are final except where required by law. Already bought? Reply to your receipt email and I’ll help. Questions before you buy? Message @yourmoneyinorder on Threads.
© 2026 Your Money In Order · Privacy Policy